The shift in who carries risk
Nigeria’s move away from administered petrol prices and the subsidy that supported them transferred a set of risks from the public balance sheet to private ones. The legal basis predates the policy: section 205(1) of the Petroleum Industry Act 2021 provides that wholesale and retail prices of petroleum products ‘shall be based on unrestricted free market pricing conditions’, and the Act makes the Nigerian Midstream and Downstream Petroleum Regulatory Authority (NMDPRA) the regulator. The decision came when President Tinubu declared at his inauguration on 29 May 2023 that ‘the fuel subsidy is gone’; on 31 May NNPC raised its pump prices from between ₦189 and ₦194 a litre to between ₦488 and ₦557, depending on region. The last administrative link went in October 2024, when NNPC gave up its role as sole buyer of Dangote petrol and marketers were left to negotiate prices with the refinery directly. Under the old arrangement a marketer’s margin was largely a policy decision. Under the new one it is the residual of import cost, exchange rate, logistics and whatever the retail market will bear.
That change is easy to state and slow to absorb. Business models, credit lines and pricing habits built for a regulated market do not adjust in a quarter. The operators that adapt fastest are likely to be those that treat the new environment as a set of exposures to be managed rather than a disruption to be waited out.
Pass-through and margin
The first exposure is timing. International product prices and the naira move daily; pump prices move when a marketer decides they can. A retailer with a strong site network and cash in hand can pass a cost increase through in the same week. A smaller operator, worried about volume, may hold prices and absorb the difference. September 2026 showed how uneven the adjustment is. On 8 September MEMAN, the association of the major marketers, estimated the landing cost of imported petrol at ₦1,311 a litre, against a Dangote gantry price of ₦1,265. Dangote raised its price by ₦85 to ₦1,350 over the weekend of 12 and 13 September, and by 14 September MRS stations in Abuja had moved from ₦1,350 to ₦1,395. When the refinery cut its price by ₦25 to ₦1,325 on Monday 21 September, pumps did not follow: the next day MRS was still selling at ₦1,395 and NIPCO at ₦1,430, and an IPMAN spokesman said members had bought their stock a few weeks earlier. MRS cut its pump price by ₦25 on 28 September. The increase reached the pump within days; the decrease took a week.
Modelling that lag, segment by segment, matters more than forecasting the level of prices. Customers respond to price changes differently by location, fuel and channel, and those responses decide how much of a cost shock a given site can recover.
Foreign exchange
Refined products are bought in dollars and sold in naira. The exchange rate has been set by trading since 14 June 2023, when the Central Bank of Nigeria (CBN) moved to a ‘willing buyer, willing seller’ model, but the instruments to hedge it remain thin. The CBN stopped quoting naira-settled non-deliverable forwards in September 2023, and no cleared dollar-naira contracts traded in 2024 or in the first four months of 2025, the Tribune reported in August 2026. Bank forwards exist but are small: in one week of late September 2026 they totalled $39.2 million, 1.49% of FX turnover, according to Nairametrics. Every depreciation between purchase and sale therefore lands on the importer’s margin. Distributors holding naira receivables face the mirror image: customers whose own costs have risen pay more slowly.
The practical response is unglamorous. Shorter credit terms, faster stock turns and a clear policy on when to reprice do more than any single hedge.
Import dependence and domestic refining
For most of the past two decades Nigeria met the bulk of its refined-product demand through imports while the state refineries ran well below nameplate capacity. The latest attempt to revive them has stalled. The Port Harcourt refinery restarted in November 2024 and was shut again in May 2025; NNPC’s group chief executive, Bayo Ojulari, said in February 2026 that utilisation had been ‘around 50 to 55 per cent’ and the plant was running at a loss. NMDPRA’s fact sheet for August 2026 recorded no output from Port Harcourt, Warri or Kaduna, and in September NNPC said that talks with prospective partners were still at the evaluation stage.
The arrival of large private refining capacity changes the supply map. The Dangote refinery began supplying petrol in September 2024, and in February 2026 it reported running its crude unit at its full nameplate capacity of 650,000 barrels a day. In August 2026, on NMDPRA data, it supplied 71% of the petrol received in Nigeria: 35.9 million litres a day from domestic refining against 14.6 million litres a day of imports, alongside its output of diesel and aviation fuel. Its crude supply is itself a commercial question. Under the naira-for-crude arrangement with NNPC, Dangote’s chief executive said in April 2026 that the refinery was receiving five cargoes a month against the 13 to 15 it expected. Domestic refining can shorten logistics chains and alter who sets the marginal price, but it also concentrates supply in fewer hands.
Operators should follow two questions. How much domestic product is actually reaching the market, and on what commercial terms? And does the import parity price still discipline domestic pricing, or has the reference shifted?
Track domestic refinery output and offtake terms against import parity each month.
Keep at least one import channel open until domestic supply has a record through a full year of maintenance cycles.
Logistics and storage
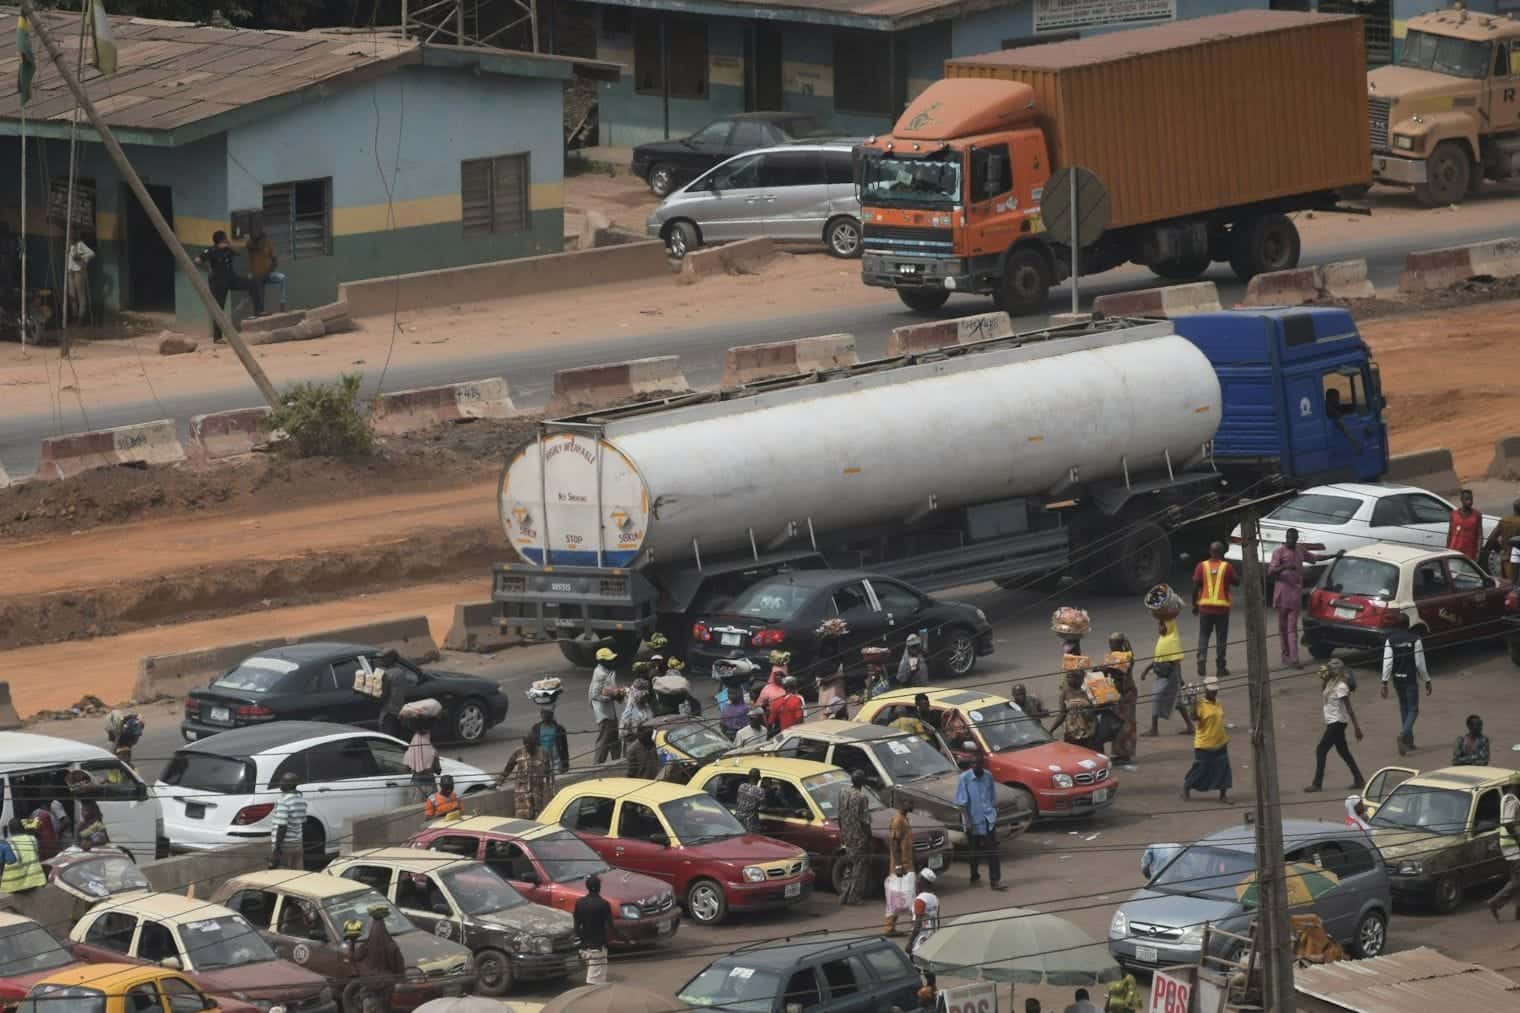
Deregulation did not build a single new tank. Storage, trucking and pipeline access remain constraints, and their cost is now a visible line in the margin rather than something absorbed elsewhere. Operators with owned or long-leased storage near demand can ride out short price swings; those on spot leases pay for flexibility they do not always get.
Retail economics and consolidation
With unit margins under pressure, volume and site quality decide who stays profitable. Larger networks with supplier credit and diversified income, from lubricants, gas and non-fuel retail, are better placed than single-site independents. Consolidation among smaller retailers is a plausible outcome over the next few years, though its pace will depend on credit conditions. Those are easing from a high base. The CBN raised its monetary policy rate from 18.75% to 27.50% over 2024, began cutting in September 2025 and reset the rate at 23% on 22 September 2026. Its data put banks’ average prime lending rate at 17.86% in August 2026 and the average maximum lending rate at 29.20%. Independent marketers, many of whom rely on bank loans to buy product, said in September that their returns were not covering the cost of that borrowing.
What to watch
Margin by segment: retail, distribution and import marketing, and when each settles at a new level.
Pass-through speed: whether pump prices now follow the naira within days or within weeks.
Domestic refining: output, product quality and the terms offered to independent marketers.
Credit: interest rates and supplier terms, which decide who can hold stock through a price swing.
Regulation: any return of price guidance, formal or informal, and how it is enforced. NMDPRA restated in September 2026 that it ‘does not fix pump prices or issue administrative price templates’, and it has agreed with the Federal Competition and Consumer Protection Commission to pursue price fixing, product withholding and under-dispensing.
Sources
Petroleum Industry Act 2021, sections 29 and 205 (Official Gazette, August 2021)
ThisDay: NNPC raises petrol price to between N488 and N557 after subsidy removal (31 May 2023)
Nairametrics: NNPC Limited confirms petrol price changes (31 May 2023)
BusinessDay: NNPC quits monopoly role in Dangote petrol (7 October 2024)
Vanguard (NAN): Motorists, commuters decry delay in petrol price cuts (22 September 2026)
Central Bank of Nigeria: Foreign exchange structure and management (accessed September 2026)
Tribune: CBN cuts OTC FX futures transaction costs by 91.5%, saves N11.6bn (10 August 2026)
Nairametrics: FX spot, derivatives drive FX trade rebound to $2.63 billion (28 September 2026)
Vanguard: Reopening Port Harcourt refinery was a waste of resources, NNPC GCEO (5 February 2026)
THEWILL: NNPC still weighing partners to revive Warri, Port Harcourt refineries (21 September 2026)
BusinessDay: Dangote supplies 71% of Nigeria’s petrol as imports plunge (24 September 2026)
Vanguard: NNPC increases crude oil supply to Dangote refinery (1 April 2026)
Central Bank of Nigeria: Monetary policy decisions, 2023 to September 2026 (accessed September 2026)
ThisDay: Relief as banking sector lending rate to businesses drop to 29.19% (21 September 2026)